Student Loan Interest Rate Forecasts 2026: What Borrowers Need to Know
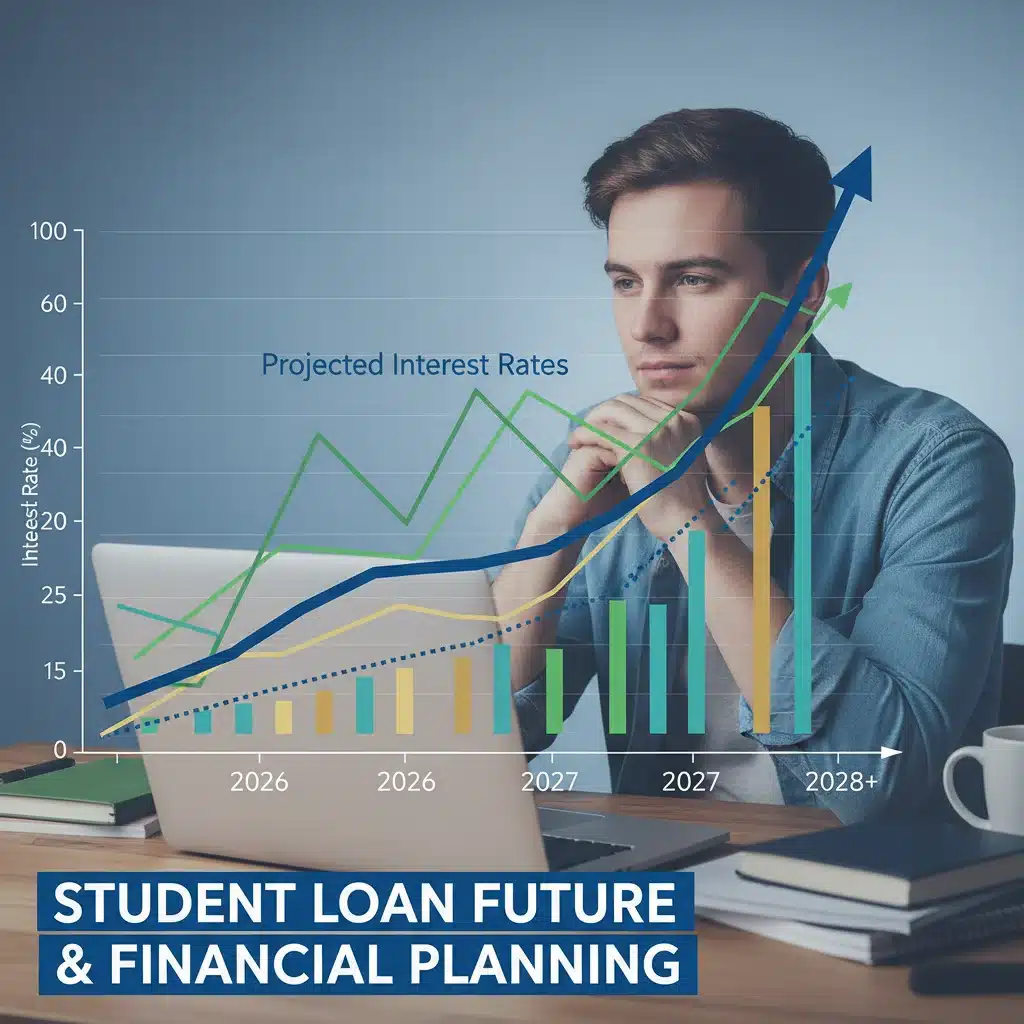
Understanding the Latest Student Loan Interest Rate Forecasts for 2026 and Beyond
For millions of students and graduates across the United States, student loans represent a significant financial commitment. The prevailing interest rates on these loans can dramatically impact the total cost of education and the long-term financial health of borrowers. As we move closer to 2026, understanding the student loan forecasts 2026 becomes paramount for effective financial planning. This comprehensive guide will delve into the various factors influencing these rates, provide insights into potential future scenarios, and offer actionable strategies for managing your student debt.
The landscape of student lending is dynamic, influenced by a complex interplay of economic indicators, governmental policies, and global events. Predicting interest rates with absolute certainty is challenging, but by analyzing current trends and expert projections, we can develop a clearer picture of what borrowers might expect in the coming years. Whether you’re a prospective student considering future borrowing, a current student navigating your financial aid package, or a graduate managing existing loans, staying informed about student loan interest rates 2026 is crucial.
The Current State of Student Loan Interest Rates
Before we look ahead, it’s essential to understand where we stand today. Federal student loan interest rates are set annually by Congress, typically tied to the 10-year Treasury note yield. Private student loan rates, on the other hand, are determined by individual lenders and are often influenced by market conditions, the borrower’s creditworthiness, and whether the rate is fixed or variable. The recent economic climate, characterized by fluctuating inflation and the Federal Reserve’s aggressive interest rate hikes, has already impacted borrowing costs across the board.
Historically, federal student loan rates have been relatively stable compared to private loans. However, even small changes can accumulate significantly over the life of a loan. For instance, an increase of just half a percentage point on a substantial loan can translate into thousands of dollars in additional repayment. This makes the student loan forecasts 2026 a critical topic for anyone with outstanding or anticipated student debt.
The pause on federal student loan payments and 0% interest during the COVID-19 pandemic offered a temporary reprieve for many borrowers. However, with payments having resumed, the focus has shifted back to managing these debts, and the future trajectory of interest rates is a major concern. Understanding the mechanisms that drive these rates is the first step in preparing for what lies ahead.
Key Economic Factors Influencing Student Loan Interest Rates
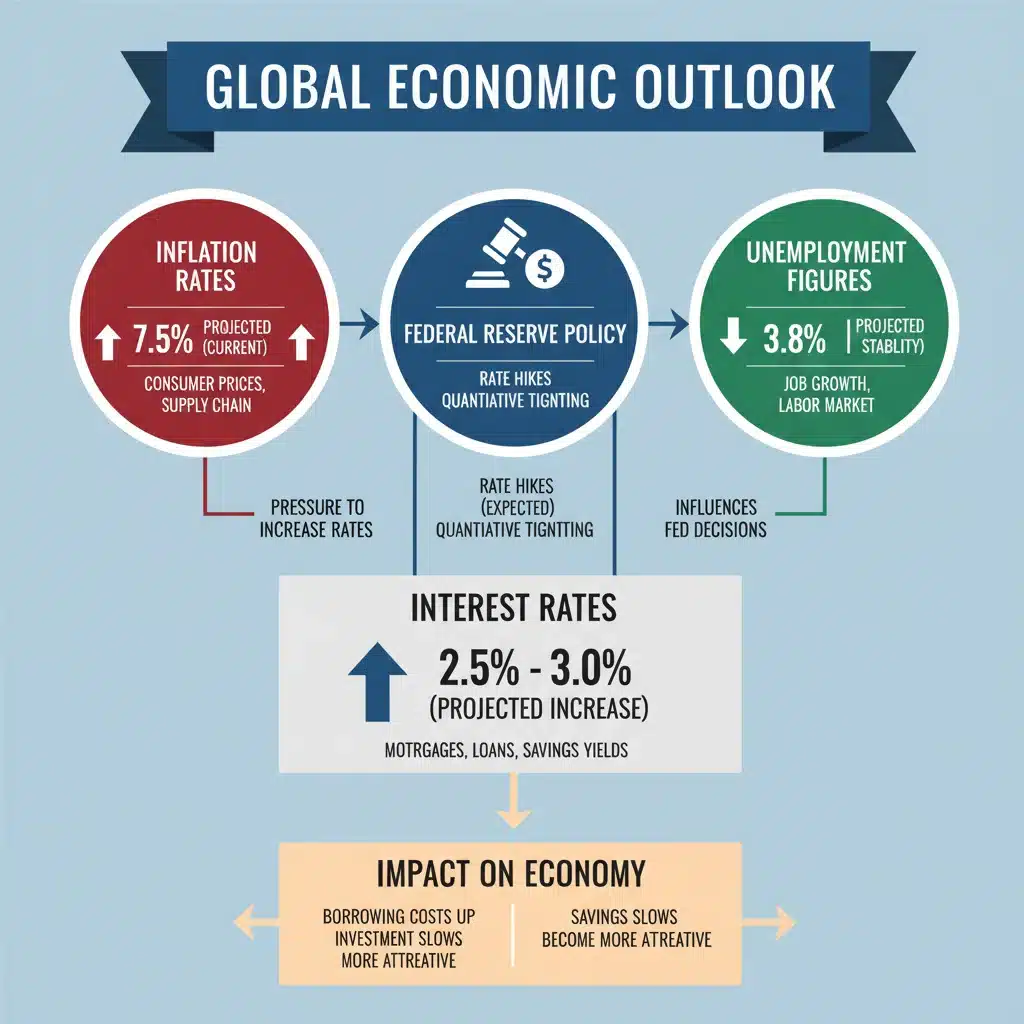
Several macroeconomic factors play a pivotal role in shaping student loan interest rates 2026. These factors interact in complex ways, making precise predictions difficult, but their general influence is well understood.
Federal Reserve Monetary Policy
The Federal Reserve (the Fed) is arguably the most influential entity when it comes to interest rates in the U.S. By raising or lowering the federal funds rate, the Fed influences borrowing costs across the entire economy, including those for student loans. When the Fed raises rates to combat inflation, as we’ve seen recently, it typically leads to higher interest rates on new loans, both federal and private. Conversely, a dovish stance by the Fed, often during economic slowdowns, can lead to lower rates.
For student loan forecasts 2026, the Fed’s future decisions will be critical. If inflation remains stubbornly high, further rate hikes are possible. If the economy cools significantly, or if inflation is brought under control, the Fed might consider rate cuts, which could offer some relief to borrowers.
Inflation Rates
Inflation erodes the purchasing power of money. To counteract this, central banks often raise interest rates. High inflation can lead to higher borrowing costs as lenders seek to maintain the real value of their returns. The persistent inflation experienced in recent years has been a primary driver of rising interest rates. The trajectory of inflation in the coming years will heavily influence whether rates continue to climb, stabilize, or begin to fall.
Economic Growth and Unemployment
A strong economy, characterized by robust GDP growth and low unemployment, often correlates with higher interest rates. In such an environment, demand for credit is high, and lenders can command higher rates. Conversely, a weakening economy or rising unemployment might prompt the Fed to lower rates to stimulate economic activity. The state of the U.S. economy leading up to and during 2026 will therefore be a significant determinant of student loan interest rates 2026.
10-Year Treasury Note Yield
Federal student loan interest rates are directly tied to the 10-year Treasury note yield. This benchmark reflects the market’s expectation of future interest rates and inflation. When the yield on the 10-year Treasury rises, federal student loan rates tend to follow suit. Monitoring this yield provides a direct indication of potential movements in federal loan rates.
Government Policy and Legislative Changes
Beyond macroeconomic factors, government policies and potential legislative changes can also significantly impact student loan interest rates and repayment terms. The setting of federal student loan interest rates is an annual congressional decision, and future administrations or legislative bodies could introduce reforms.
Potential Legislative Reforms
Discussions around student loan reform are ongoing. Proposals range from simplifying the federal student aid application process to overhauling the interest rate setting mechanism. While large-scale legislative changes are often slow and politically charged, even minor adjustments could affect how student loan forecasts 2026 play out. For instance, a move towards fixed rates for all federal loans or a cap on interest rates could provide greater predictability and potentially lower costs for borrowers.
Impact of Presidential Administrations
The policies of a given presidential administration can also influence the student loan landscape. While the President doesn’t directly set interest rates, their administration can advocate for specific legislative changes, implement new regulations, and direct executive actions that affect student loan programs. Future elections and shifts in political priorities could therefore introduce new variables into the student loan interest rates 2026 equation.
Expert Predictions and Scenarios for 2026
Gathering insights from economists and financial analysts offers a glimpse into potential student loan forecasts 2026. While no one has a crystal ball, these predictions are based on current economic models and projections.
Scenario 1: Continued High Rates
If inflation remains elevated and the Federal Reserve continues its tightening monetary policy, we could see student loan interest rates remain at their current high levels or even increase further. This scenario would mean higher borrowing costs for new loans and potentially less favorable refinancing options for existing ones. Borrowers would need to be particularly diligent in managing their debt under these conditions.
Scenario 2: Moderation and Stability
A more optimistic scenario suggests that inflation will gradually recede, allowing the Federal Reserve to pause or even begin to cut interest rates. In this case, student loan interest rates 2026 might stabilize or experience a modest decrease. This would offer some relief to borrowers and could make higher education more accessible.
Scenario 3: Economic Downturn and Lower Rates
In the event of a significant economic recession, the Federal Reserve would likely cut interest rates aggressively to stimulate growth. This could lead to a substantial decrease in student loan interest rates. While lower rates would be beneficial for borrowers, an economic downturn also brings challenges like job insecurity, which could complicate repayment for many.
It’s important to remember that these are scenarios, not guarantees. The actual path of interest rates will depend on a multitude of evolving factors. Staying informed about economic news and expert analyses will be key to understanding the most likely outcome for student loan forecasts 2026.
Strategies for Managing Student Debt in a Changing Rate Environment
Regardless of what the student loan forecasts 2026 hold, borrowers have several strategies at their disposal to effectively manage their student debt. Proactive planning can mitigate the impact of rising rates and optimize repayment.
Understanding Your Loan Types
Distinguish between federal and private loans. Federal loans often come with more flexible repayment options, such as income-driven repayment (IDR) plans, deferment, and forbearance. Private loans typically have fewer protections but might offer lower rates for borrowers with excellent credit. Knowing your loan types is the first step in choosing the right management strategy.
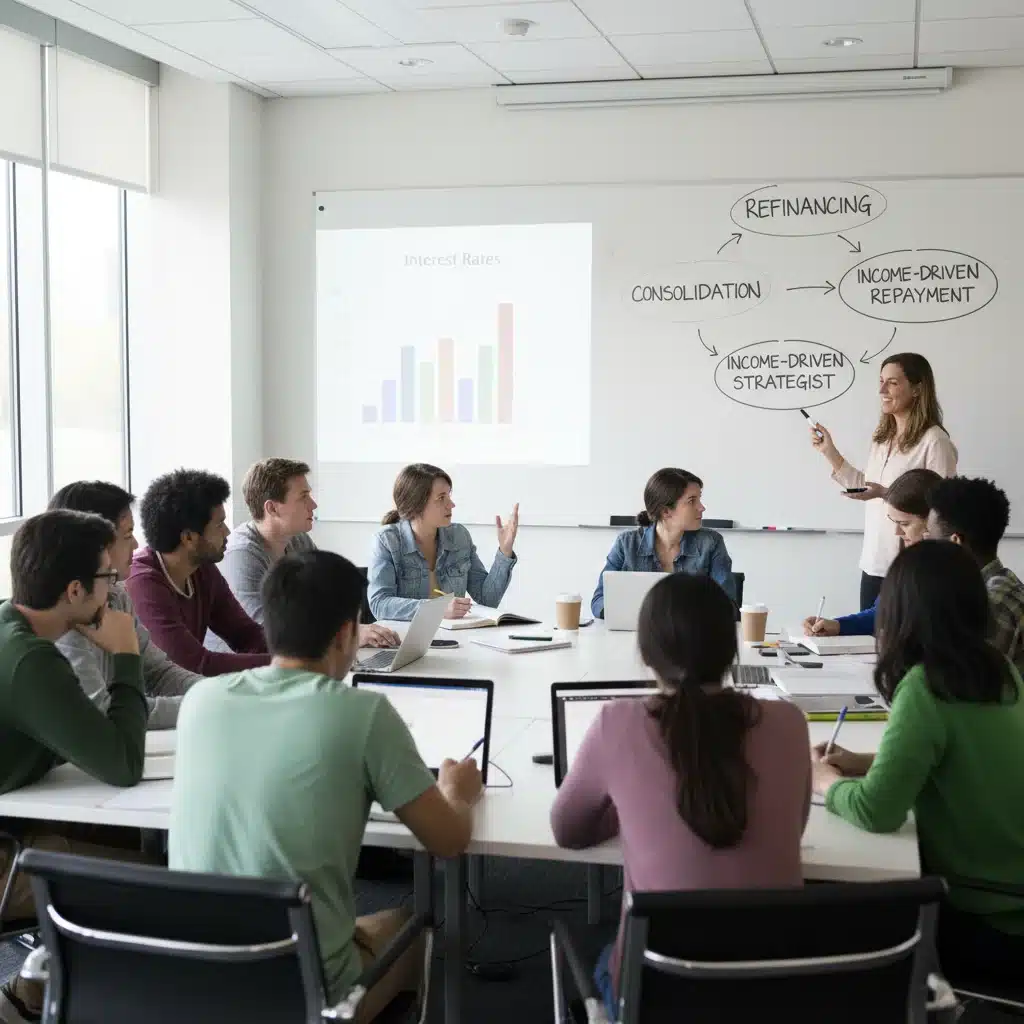
Exploring Income-Driven Repayment (IDR) Plans
For federal loan borrowers, IDR plans can be a lifeline. These plans adjust your monthly payment based on your income and family size, potentially making your payments more affordable, especially if your income is modest. Some plans also offer loan forgiveness after a certain number of years of qualifying payments. This is a crucial consideration, especially if student loan interest rates 2026 are expected to remain high.
Refinancing Private Student Loans
If you have private student loans and your credit score has improved since you first took them out, or if interest rates decline, refinancing could be a viable option. Refinancing replaces your existing loans with a new loan, ideally with a lower interest rate or more favorable terms. Carefully compare offers from multiple lenders and understand the trade-offs, such as potentially losing federal loan protections if you refinance federal loans into a private one.
Consolidating Federal Student Loans
Federal loan consolidation allows you to combine multiple federal student loans into a single new loan with a single monthly payment. The interest rate for a Direct Consolidation Loan is the weighted average of your original loans’ interest rates, rounded up to the nearest one-eighth of a percentage point. While it might not lower your interest rate, it can simplify repayment and potentially open up eligibility for certain IDR plans or Public Service Loan Forgiveness (PSLF).
Making Extra Payments
Even small extra payments can significantly reduce the total interest paid over the life of your loan. If your budget allows, consider paying more than the minimum required, especially on loans with higher interest rates. This strategy is particularly effective in a high-interest rate environment, helping to minimize the impact of elevated student loan interest rates 2026.
Building an Emergency Fund
An emergency fund provides a financial safety net, preventing you from missing loan payments if unexpected expenses arise. This is crucial for maintaining good credit and avoiding default, especially in uncertain economic times. Having a robust emergency fund can provide peace of mind regardless of the student loan forecasts 2026.
The Role of Financial Literacy and Planning
Navigating the complexities of student loans requires a solid foundation in financial literacy. Understanding how interest accrues, the implications of different repayment plans, and the long-term impact of your borrowing decisions is vital. As we look towards student loan forecasts 2026, empowering yourself with knowledge is your best defense against financial uncertainty.
Seeking Professional Advice
Don’t hesitate to consult with a financial advisor or a student loan counselor. These professionals can help you understand your specific situation, explore personalized strategies, and navigate the intricacies of student loan repayment options. They can also provide insights into how general student loan interest rates 2026 might affect your personal financial plan.
Regularly Reviewing Your Loans
The student loan landscape can change. It’s wise to periodically review your loan statements, understand your current interest rates, and reassess your repayment strategy. This ongoing review ensures that you’re always on the most advantageous path, especially as economic conditions and interest rate forecasts evolve.
Potential Impact on Future Students
The student loan forecasts 2026 are not just relevant for current borrowers; they also have significant implications for prospective students. High interest rates can make higher education more expensive, potentially influencing decisions about college choice, major, and overall financial planning.
Consideration of College Costs
Prospective students and their families should factor in potential interest rate environments when estimating the total cost of a degree. A higher interest rate means a greater overall cost, which might lead some to consider more affordable educational pathways, community college first, or vocational training.
Maximizing Grants and Scholarships
In an environment of potentially higher interest rates, maximizing grants and scholarships becomes even more critical. These forms of financial aid do not need to be repaid and can significantly reduce the amount of money a student needs to borrow, thereby lessening their exposure to fluctuating interest rates.
Understanding Loan Limits and Borrowing Responsibly
Future students should be acutely aware of federal and private loan limits and strive to borrow only what is absolutely necessary. Over-borrowing, especially at higher interest rates, can lead to substantial financial strain post-graduation. Understanding the student loan interest rates 2026 can help inform these crucial borrowing decisions.
Conclusion: Preparing for the Future of Student Loans
The journey through higher education and beyond is often intertwined with student loan debt. As we look towards student loan forecasts 2026, it’s clear that vigilance, informed decision-making, and proactive financial planning will be paramount. While the exact trajectory of interest rates remains subject to a complex array of economic and political forces, understanding the influencing factors and preparing for various scenarios can empower borrowers.
By staying abreast of Federal Reserve actions, inflation trends, and potential legislative changes, borrowers can better anticipate shifts in student loan interest rates 2026. Furthermore, by actively exploring repayment options, considering refinancing when advantageous, and practicing sound financial habits, individuals can navigate their student loan obligations more effectively, ensuring a healthier financial future.
The landscape of student finance is ever-evolving, but with the right knowledge and strategies, you can confidently face the challenges and opportunities that lie ahead in managing your student debt. Start planning today to secure your financial well-being for 2026 and beyond.